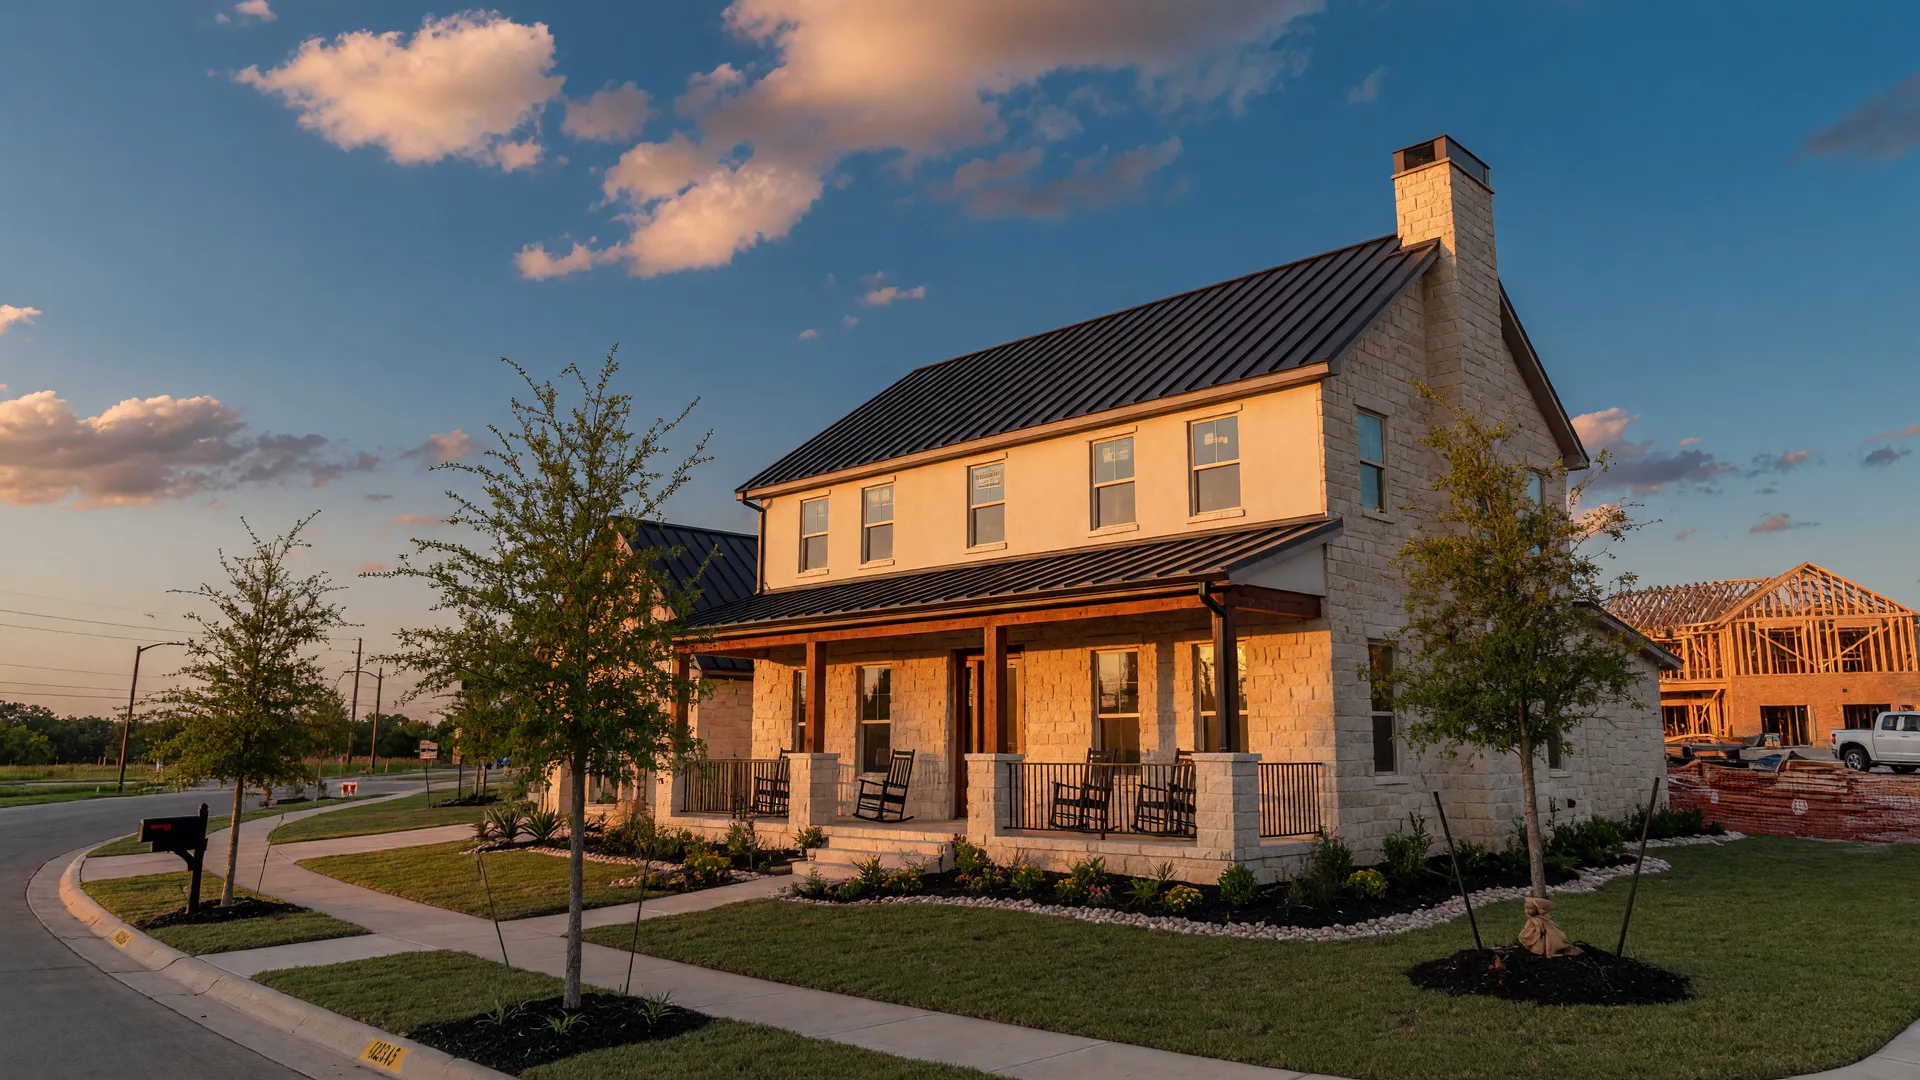
A veteran's VA benefit is one of the most powerful homeownership tools in America, and more veterans should know it goes far beyond buying a resale. With the VA one-time close construction loan, qualified veterans, active-duty service members, Guard and Reserve members, and qualifying surviving spouses can build a brand-new custom home with no down payment, combining the land, the build, and the permanent 30-year mortgage into one loan with one closing. If you have ever thought, "I wish I could build," this is exactly how you turn that wish into a plan.
What Is the VA One-Time Close Construction Loan?
The VA one-time close construction loan, also called a single-close or construction-to-permanent loan, wraps the entire project into one package: the land purchase, if you need to buy the lot, plus the construction financing, plus the permanent 30-year VA mortgage. Everything closes together as a single loan.
That means one application, one set of closing costs, and one closing date. When construction finishes, there is no second closing, no second set of loan fees, and no need to requalify on credit. In August 2025, the VA launched a standardized single-close construction loan program, and that made this route meaningfully easier for veterans than it had been before. If you qualify, this is one of the cleanest, most direct paths to a brand-new home in the entire mortgage market.
Building With Nothing Down
Here is the headline number, and it deserves a moment: qualified veterans with full entitlement can finance up to 100% of the land and build costs. That is $0 down on a custom home.
There is no private mortgage insurance either, even at full financing. That is a real monthly saving, because conventional construction loans almost always charge mortgage insurance when you finance at high loan-to-value, and they typically demand 10% to 25% down before you ever break ground. The VA funding fee may also be rolled into the loan, so you can keep your out-of-pocket costs to a minimum.
Add it up and the gap is thousands of dollars wide. A family building with a conventional construction loan needs a big pile of cash just to start. With the VA one-time close loan, the same family can put nothing down and keep their savings for the things that matter: finishes, landscaping, and the months between groundbreaking and move-in.
One Closing Beats Two
Building a home used to mean two loans and two closings: one to finance the land and construction, and a second, later mortgage once the house was finished. The VA one-time close loan collapses that into a single event.
You save more than paperwork. One closing means one set of closing costs instead of two. It means your interest rate is locked in up front rather than renegotiated at the end of the build, when you have the least leverage. And because your credit is approved once, a market shift or a change in your finances during construction cannot force you to requalify. Many lenders also offer no payments during the construction period, so you are not juggling a construction payment and your current housing costs at the same time. The simplicity is the point: one loan, one closing, then you move in.
Who Can Use It
Eligibility follows the standard VA loan rules. You need to be an eligible veteran, an active-duty service member, a National Guard or Reserve member, or a qualifying surviving spouse, with a valid VA Certificate of Eligibility (COE).
The home must be your primary residence. This is not a program for second homes, rentals, or speculative builds. You will build with a licensed, insured builder using approved plans, and the VA appraisal is based on the home's completed value rather than its unfinished state.
On credit, the VA sets no official minimum score, but most lenders look for credit in the mid-600s and up, commonly cited at 620 or higher, and standard income and residual income guidelines apply. The good news is that the VA loan is famously forgiving when it comes to credit history. If you are still learning the basics of the benefit, our guide to VA loans explained walks you through the whole program, from entitlement to closing.
Why This Matters in Central Texas
Central Texas is one of the best markets in the country to put this benefit to work. Texas has no state income tax, so more of your household income stays in your pocket every paycheck. The cost of living across Temple, Belton, and the surrounding communities is dramatically lower than the big metro areas, which means the same VA entitlement buys more house, more land, and more options.
Fort Cavazos brings one of the strongest military communities in the nation, and this entire region is built around families who understand the rhythms of service life. If you are settling in the Temple, Belton, or greater Central Texas area, a custom build powered by a VA one-time close loan can deliver more home for the money than almost any other path: new construction, your layout, your finishes, your acreage, at a price point that still makes sense.
If you are weighing your options, our side-by-side breakdown of VA loans versus conventional loans shows exactly where each program wins, so you can compare the two before you decide.
Key Takeaway
You have earned the right to build the home you want. The VA one-time close construction loan lets you do it with nothing down, one closing, and a benefit designed for those who served.
Your Next Step
Here is how to start. Talk to a lender who knows VA construction inside and out, because there are specialists who work with the one-time close structure every day and can verify your numbers before you commit a dollar. Get your Certificate of Eligibility if you do not already have it. Line up a licensed, insured builder with approved plans that fit your budget. Then start the conversation about what your finished home should look like.
The VA one-time close loan is a rare mortgage moment: a program built specifically for those who served, and it turns "I wish I could build" into "I can build." My team and I help veterans and their families navigate custom builds every day, from the first lender call to the final walkthrough. We would be honored to help you plan yours.
Veteran-Ready
Ready to Build With Your VA Benefit?
Lisa is a Military Relocation Professional who helps veterans and their families build custom homes across Central Texas, from the first lender call to the final walkthrough.
Lisa Copeland
Visit Lisa's speaker and author site at lisacopeland.com.
Lisa Copeland is the dominant market leader in Central Texas real estate and leads a 900+ Agent real estate organization operating across 29 countries that has closed more than 5 billion in sales over the last six years. She holds the Military Relocation Professional designation and has guided hundreds of military families to successful home purchases and custom builds across the Fort Cavazos region.